Flat-steel and coating input costs moved decisively higher during the second and third weeks of November 2026, reshaping raw material budgets for cold roll forming plants and welded tube mills heading into Q1 2027. In the United States, Nucor raised its hot-rolled coil Consumer Spot Price for a seventeenth consecutive week on November 16 to $1,310 per short ton, while broader spot assessments climbed toward $1,390 per short ton. In Europe, Northwest Europe hot-dip galvanized (HDG) coil reached €860 per tonne ex-works as mills quoted €790 to €800 per tonne for Q1 2027 hot-rolled substrate. At the same time, London Metal Exchange (LME) zinc settled between $3,732 and $3,848 per tonne in mid-November, keeping galvanizing surcharges high, while South Korean steelmakers requested duties on Chinese galvanized coil on November 9. For fabricators converting slit strip into purlins, structural channels, and ERW pipe, the price spread between raw coil regions and the rising cost of zinc coatings now directly dictate scrap tolerance, inventory turnover, and equipment efficiency.
US Hot-Rolled Coil Extends Its 17-Week Climb
On Monday, November 16, 2026, Nucor lifted its weekly hot-rolled coil Consumer Spot Price (CSP) by $15 per short ton to $1,310, bringing its cumulative increase since September 8 to $120 per short ton. Its West Coast joint venture, California Steel Industries, matched the $15 move to reach $1,380 per short ton. Independent transaction assessments sit even higher: Steel Market Update placed the wider US hot-rolled coil market between $1,340 and $1,440 per short ton, averaging $1,390 per short ton, with CME US Midwest front-month futures settling near $1,353 per short ton on November 13.
Mill lead times confirm why weekly hikes have met minimal buyer resistance. While Nucor kept its published spot lead time at three to five weeks, broader US sheet lead times averaged 9.7 weeks across surveyed buyers in mid-November. Converted to metric tonnes, Nucor's list price equals roughly $1,444 per metric tonne—nearly three times the $478.50 per tonne reference seen for Chinese export hot-rolled coil on the LME. A North American roll forming plant purchasing 1,000 short tons of coil now commits about $1.31 million in working capital, compared with roughly $845,000 during the same week of 2025. When strip accounts for 70 to 80 percent of finished section cost, a 52 percent year-on-year substrate increase leaves zero margin for setup scrap or over-ordered coil widths.
European Galvanized Coil Climbs to €860/t Ahead of Q1 2027
European flat-steel producers entered mid-November with 2026 rolling schedules largely filled and Q1 2027 contract negotiations pointing upward. For the week ending November 6, Northwest Europe hot-dip galvanized coil was assessed at €860 per tonne ex-works, up €10 week on week. Mills are quoting €790 to €800 per tonne for Q1 2027 hot-rolled coil, with several producers indicating that first-quarter allocations are already nearing sell-out due to scheduled mill maintenance. On November 13, ArcelorMittal reinforced this trajectory, stating that European steel prices are expected to increase through Q4 with a constructive pricing outlook carrying into early 2027.
For European roll formers producing building frames, solar brackets, and cable management profiles, the cost pressure is concentrated in coated strip. Annual contract offers for 2027 have been reported up to €150 per tonne above prior benchmarks. Buyers cannot simply replace domestic HDG coil with low-cost imports without absorbing quarterly safeguard quota risk and documentation requirements, making domestic European strip utilization a central metric for plant profitability.
Elevated LME Zinc and Asian Coated-Coil Trade Friction
Coated strip buyers face a second cost floor from the zinc market. LME zinc cash settlement prices remained elevated through mid-November 2026, closing at $3,848 per tonne on November 16, $3,776 on November 17, and $3,732 on November 18, while LME warehouse stocks hovered near 146,775 tonnes. Sustained zinc prices above $3,700 per tonne hold galvanizing levies high—Australian structural fabricators, for instance, faced a 27.94 percent zinc levy in November, easing only modestly to 24.56 percent for December.
Simultaneously, trade defense pressure has shifted directly onto coated coil in Asia. On November 9, South Korean steelmakers formally called for duties on Chinese hot-dip galvanized iron (HGI) coil to stem coated-strip inflows. For overseas roll forming plants that previously relied on pre-galvanized Asian strip, expanding coated-product trade actions signal that substrate routing and coating specifications—whether Z275 hot-dip galvanized or Zinc-Aluminum-Magnesium (ZAM) alloy—must be locked into supplier contracts earlier in the procurement cycle.
Mid-November 2026 Raw Material Snapshot
| Market / Benchmark | Mid-November 2026 Level | Recent Movement | Operational Impact on Fabricators |
|---|---|---|---|
| US Nucor HRC CSP | $1,310/st ($1,444/mt) | 17th straight weekly hike; +$120/st since Sept 8 | Higher working capital; strict scrap limits |
| US Broader HRC (SMU) | $1,340–$1,440/st (avg $1,390) | Average lead time at 9.7 weeks | Longer coil replenishment cycles |
| NW Europe HDG Coil | €860/tonne ex-works | +€10/t w/w; Q1 2027 HRC offers €790–€800/t | Rising Q1 2027 coated-strip budgets |
| LME Zinc Cash Settlement | $3,732–$3,848/tonne | Firm above $3,700/t; stocks ~146,775 t | Sustained galvanizing surcharges on Z275/ZAM |
| South Korea HGI Trade | Domestic mills seek duties on Chinese HGI | Formal industry demand on Nov 9 | Tighter regional routing for pre-galvanized strip |
India Mill Expansion and Global Steel Tube Demand
Outside the Atlantic pricing surge, capital investment in construction and pipe-grade steel continues to accelerate across high-growth regions. On November 16, India's Tata Steel announced plans to build two scrap-based electric-arc steel mills dedicated to construction-grade steel, reinforcing India's trajectory as the fastest-growing major steel market. Meanwhile, a global metal pipe market outlook published on November 18 projected the sector to reach $190.4 billion by 2035 at a 4.4 percent compound annual growth rate from 2026, supported by energy transport, urban water infrastructure, and industrial structural hollow sections.
In regions where construction-grade flat steel is expanding—such as India, Southeast Asia, and the Middle East—demand for structural hollow sections and precision welded tubing is rising alongside coil availability. Fabricators operating a dedicated steel tube and pipe mill line or high-frequency ERW tube mill line can convert local hot-rolled strip into square, rectangular, and round structural tubes while maintaining tight wall-thickness control and low weld-trim loss.
How Roll Forming Plants Protect Margins Under $1,300+ Coil
When hot-rolled strip exceeds $1,300 per short ton in North America and galvanized coil sits at €860 per tonne in Europe, raw material efficiency outweighs minor differences in labor or electricity cost. Four mechanical and operational upgrades deliver immediate payback in high-coil-cost environments:
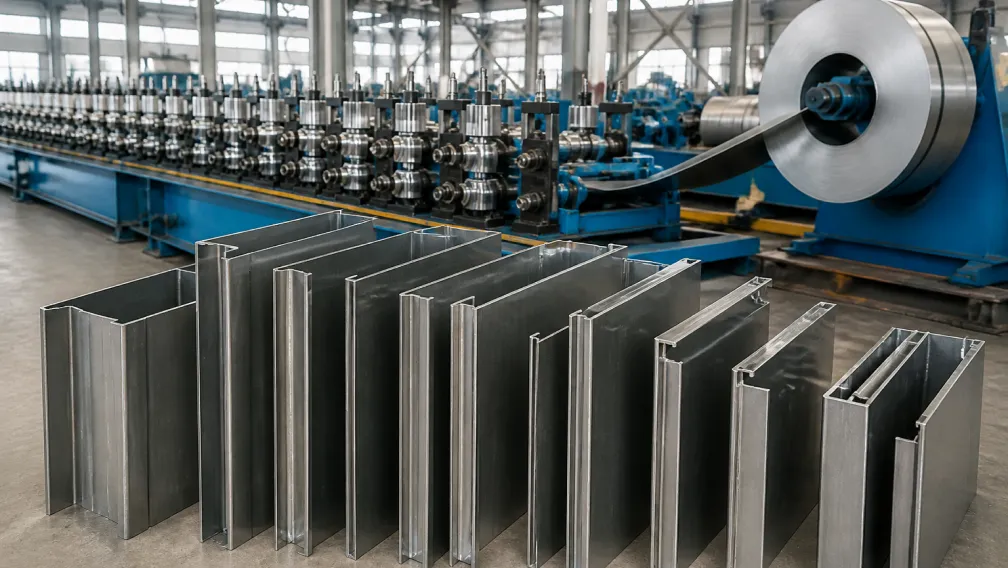
- Zero-waste profile changeover: On legacy roll formers, every manual width or depth changeover sacrifices 10 to 30 meters of test strip during roll-gap dialing. Upgrading to motorized width and depth adjustment on a CZ purlin roll forming machine or multi-size profile production line cuts trial scrap to a single test piece while letting plants hold fewer slit-coil widths in stock.
- Coating-safe tooling geometry: With LME zinc above $3,700 per tonne, flaking or zinc galling on Z275 and ZAM strip causes costly rejections. Gradual bend progressions and vacuum-hardened, mirror-polished Cr12MoV rollers preserve coating continuity across tight inner radii.
- Coil-end welding and accumulator integration: Joining the tail of an expiring coil to the lead edge of the next strip via an automatic shear-and-end-welder eliminates tail-end cropping losses—recovering 1.5 to 2.5 percent of annual steel consumption on continuous lines.
- ERP-linked batch length optimization: Running an automatic roll forming machine with PLC batch sequencing and flying tracking cut-off allows plants to nest mixed project lengths from a single master coil, reducing remnant drop lengths and working capital tied up in finished inventory.
Configure High-Yield Forming Lines for 2027 Budgets
High coil prices and extended mill lead times reward plants that extract maximum finished tonnage from every tonne of strip delivered to the floor. THRONCH engineers high-yield cold roll forming lines and ERW tube mills equipped with motorized quick-changeover stands, precision servo punching, shear-and-end-welders, and automated stacking to minimize scrap on expensive galvanized and high-tensile coils. Send your target profile drawings, strip thickness range, and 2027 production plan to amy@thronch.com for a detailed configuration proposal.
-

THRONCH
Cold Roll Forming Machine Manufacturer
THRONCH is a direct manufacturer specializing in custom cold roll forming lines and welded pipe mills. With over a decade of engineering expertise, we share technical insights and deliver high-precision